The UK is a nation of pet lovers: over 57% of us own a pet. Trips to the vet can be expensive, though, especially for new, advanced treatments, which means that many owners buy insurance.1
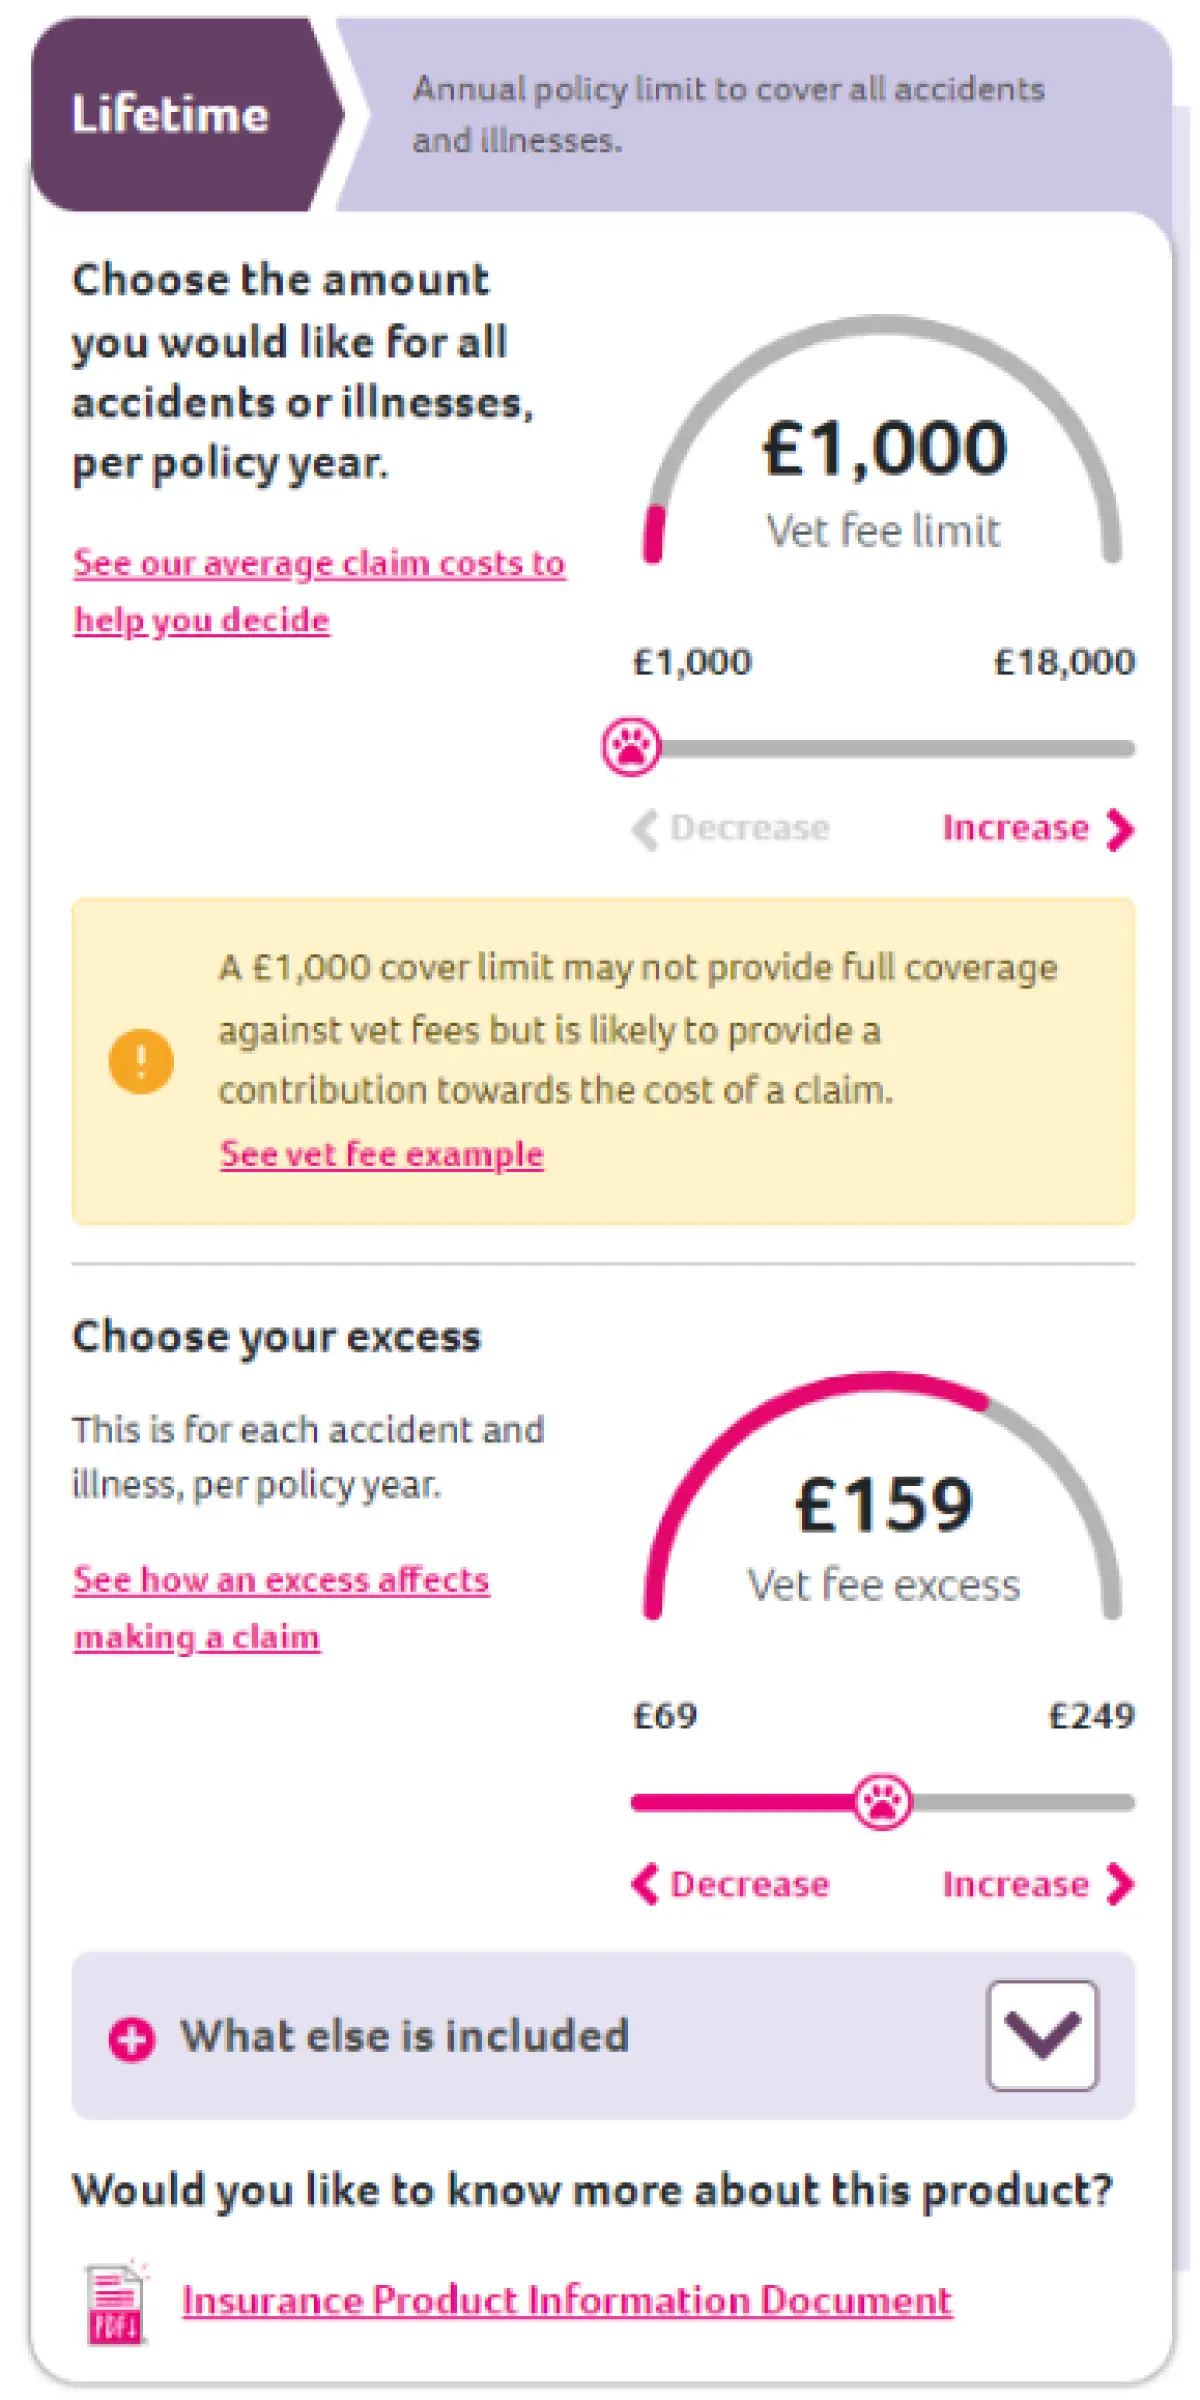
One type of pet insurance is lifetime cover. Lifetime policies provide the most comprehensive cover of all the types of pet insurance. As the cost of veterinary treatment will rise over the course of the pet’s lifetime, these policies are designed to offer continued peace of mind, covering accidents, illnesses and any conditions your pet may develop throughout their lifetime. They also have a defined yearly amount of cover that will reset, with no lapses in cover when the policy is renewed, and the amount of cover can be increased, usually at renewal.2
The pet insurance market has become increasingly complex in recent years when it comes to lifetime cover, though, which can make it difficult for customers to work out what is the best coverage for their pet.
This blog looks at how providers can do better to help guide their customers to finding the right products.
The number of lifetime policies has risen
During the past six years, the pet insurance market has become more crowded as a sector. This isn’t because there are more insurers in the market. In fact, there are fewer providers offering pet insurance than in 2018. Instead, what’s happened is that there has been an increase in the number of policies on offer. This has had the result of giving customers more choice, but has also added complexity, potentially making it harder for customers to select the right policy for their needs.
According to Fairer Finance data, the relative shares of different types of pet insurance policies being sold has changed dramatically since 2018. Time limited, maximum benefit, and accident-only policies have declined, while the number of lifetime policies currently being offered has increased by 105% from 139 to 286.